Why the Busch vs Pacific Life Case Matters for Retirement Planning and Investor Protection

The Busch vs Pacific Life lawsuit has escalated into the federal court system, marking a pivotal moment for Indexed Universal Life (IUL) policies and the broader financial services industry. What began as a state‑level dispute is now a nationally visible case that could reshape how retirement strategies are marketed and understood.

Background Recap

Kyle and Samantha Busch allege that Pacific Life and advisor Rodney Smith misrepresented IUL policies marketed as “tax‑free retirement plans.”

  • Over $10.4 million in premiums paid
  • $8.58 million in net losses claimed
  • Alleged 35% commission (~$3.64 million) taken before funds reached Pacific Life
  • Promises of guaranteed multipliers and tax‑free income that did not materialize

The Busches argue this was not simply poor performance, but a pattern of fraud and misrepresentation. For readers who want a deeper dive into the full timeline, claims, and mechanics of this case, see our detailed breakdown here.
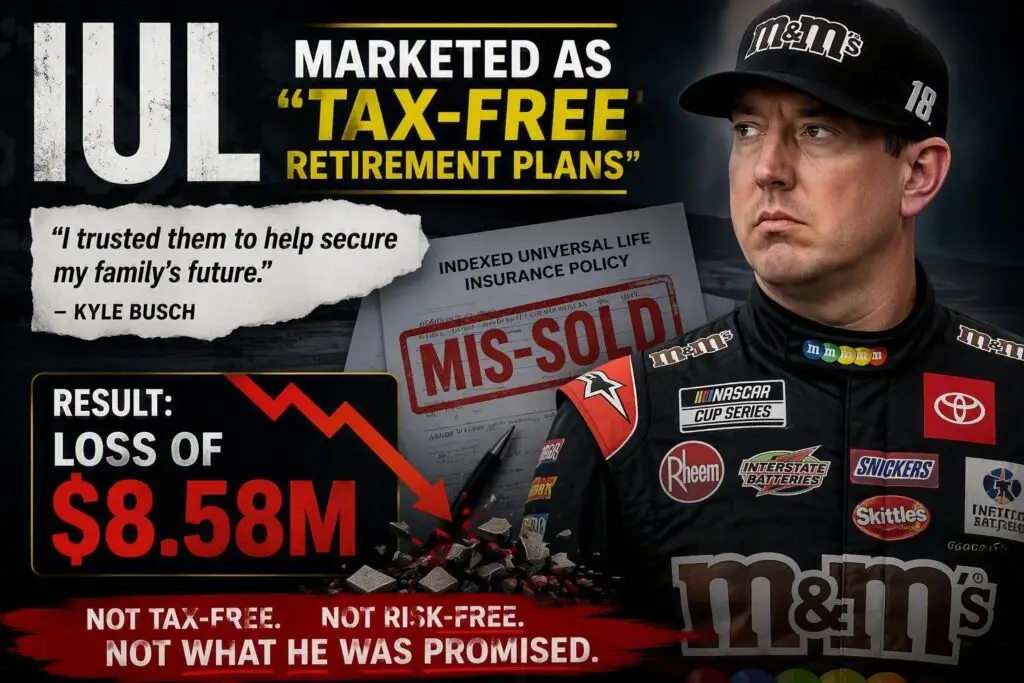
Graphic discussing Indexed Universal Life (IUL) insurance, featuring a claim of "tax-free retirement plans" alongside a highlighted loss of $8.58 million and concerns about policy misrepresentation.

Executive Summary

  • Case Escalation: The Busch vs Pacific Life lawsuit has moved from North Carolina state court into federal jurisdiction, amplifying its visibility and extending the timeline.
  • Pacific Life’s Stance: The insurer has avoided commenting on specific allegations, instead emphasizing its 160‑year commitment to fairness and integrity.
  • Plaintiffs’ Intent: The Busches appear determined to pursue the case aggressively, framing it as a broader indictment of IUL sales practices.
  • Industry Impact: Discovery could expose internal training, illustration software, and commission structures, potentially reshaping compliance standards.
  • Investor Takeaway: Transparency, advisor accountability, and realistic expectations are critical safeguards for anyone considering IUL as part of their retirement strategy.

Pacific Life's Public Stance

Pacific Life petitioned to move the case into federal court, citing diversity jurisdiction. In public statements, the company has avoided specifics, instead emphasizing:
kyle busch vs pacific life covered by M&M Wealth Associates

"For nearly 160 years, we have committed ourselves to fairness, integrity, and acting in the best interests of our clients and we continue to take this responsibility very seriously. Pacific Life offers several different life insurance products, each with unique characteristics that are important to understand before making a decision."

This values‑based messaging reflects a strategy of legal defense and reputation management rather than direct engagement with the allegations.

The Busches’ Intent

The plaintiffs appear determined to press forward, framing the case as a broader indictment of IUL sales practices. Their intent is not only to recover losses but to spotlight systemic issues in how these products are marketed.

What Federal Court Means

  • Broader Jurisdiction: Federal law applies, not just North Carolina statutes.
  • Longer Timeline: Motions, discovery, and trial could stretch well into 2026.
  • Discovery Impact: Internal training, illustration software, and commission structures may be revealed.
  • National Visibility: Regulators, media, and industry leaders are watching closely.

Implications for Investors & Advisors

This case raises fundamental questions about IUL marketing and advisor accountability:

  • Transparency: Clients must understand costs, risks, and realistic returns.
  • Advisor Accountability: Disclosure of commissions and disciplinary history is critical.
  • Compliance Standards: The outcome could reshape illustration rules and sales practices across the industry.

For investors, the lesson is clear: demand clarity, ask hard questions, and ensure your retirement strategy is built on trust.

Looking Ahead

Pacific Life is expected to file motions to dismiss or limit claims. Discovery could expose internal practices, and whether the case settles or proceeds to trial, its impact will ripple across the financial services landscape. 

Closing Reflection

The Busch vs Pacific Life lawsuit is a reminder that financial strategies must be built on clarity and trust. For families and business owners exploring life insurance for retirement planning, Indexed Universal Life offers a way to combine protection with growth.

Unlike traditional accounts, IUL can provide tax free income in retirement, downside protection when markets dip, and living benefits that safeguard against unexpected health challenges. These features make IUL a flexible ally for those seeking both security and opportunity in their retirement strategy.

At M&M Wealth Associates, we believe education and transparency are the best safeguards for your legacy. As this case unfolds, we remain committed to guiding families through complex decisions with honesty, expertise, and care. For a deeper dive into how IUL creates tax free retirement income and protects against market losses, see our full breakdown here.

Privacy Policy

M&M Wealth Associates values your privacy and is committed to helping make your experience with our website safe, secure, and informative. This Privacy Policy explains how we collect, use, and share information you provide when accessing or using our website.


Your Acknowledgement

This website is intended for use by individuals who are at least 18 years of age and who are accessing the website from within the United States.

By using this website or submitting information through it, you acknowledge that:

  • You are at least 18 years old.
  • You are accessing the website from within the United States.
  • You consent to the collection, use, and sharing of information as described in this Privacy Policy.

This Privacy Policy is incorporated into and subject to the website’s Terms of Use.


Information We Collect

We may collect both personally identifiable information (“PII”) and non-personally identifiable information (“Non-PII”).

Personally Identifiable Information (PII)

Examples include:

  • Name
  • Address
  • Email address
  • Phone number
  • ZIP code
  • Other information voluntarily submitted through forms or inquiries

Non-Personally Identifiable Information (Non-PII)

Examples include:

  • IP address
  • Browser type
  • Device information
  • Domain names
  • Access dates and times
  • Website usage data

For purposes of this Privacy Policy, both categories may be referred to collectively as “Information.”


How Information Is Collected

We may collect information when you:

  • Complete a contact form
  • Request information
  • Schedule a consultation
  • Access resources available through the website

We may also automatically collect certain information through cookies, browser information, analytics tools, and similar technologies.

Information automatically collected may include:

  • IP address
  • Browser type
  • Device identifiers
  • System type
  • Pages visited
  • Referring website addresses
  • Usage and navigation data

Cookies may be used to improve website functionality, personalize user experiences, and support website analytics.


How We Use Information

Information collected through the website may be used to:

  • Respond to requests and inquiries
  • Provide information and educational resources
  • Discuss insurance or financial products and services
  • Personalize communications
  • Improve website functionality and user experience
  • Maintain website security
  • Prevent fraud or misuse
  • Develop new services and website features
  • Fulfill legal and regulatory obligations

Information Sharing

We may share information with service providers and business partners who assist us in operating our business and servicing client needs.

We may also disclose information when:

  • Required by law
  • Responding to court orders, subpoenas, or regulatory inquiries
  • Protecting our rights, property, or safety
  • Investigating fraud, abuse, or unlawful activity
  • Enforcing our website terms and agreements

Communications and Your Right to Opt Out

By submitting information through this website, you consent to being contacted through the information you provide, including by:

  • Telephone
  • Email
  • Mail
  • Text message, where permitted by law

You may opt out of future promotional communications at any time.

To request removal from promotional communications, please contact:

M&M Wealth Associates
2900 S Harbor Blvd, Suite 225
Santa Ana, CA 92704

Phone: (714) 494-9515

Please allow up to 10 business days for processing. Administrative or legally required communications may still be sent when permitted by law.


Information Security

We maintain reasonable administrative, technical, and physical safeguards designed to protect information from unauthorized access, use, disclosure, alteration, or destruction.

However, no method of transmission or storage is completely secure, and we cannot guarantee absolute security.

If a security incident occurs, we may notify affected individuals electronically when permitted by law.

If you believe website security has been compromised, please contact us at:

(714) 494-9515


Changes to This Privacy Policy

M&M Wealth Associates reserves the right to update or modify this Privacy Policy at any time.

Changes become effective immediately upon posting to the website. Continued use of the website constitutes acceptance of any updated Privacy Policy.


Contact Us

If you have questions regarding this Privacy Policy, please contact:

M&M Wealth Associates
2900 S Harbor Blvd, Suite 225
Santa Ana, CA 92704

Phone: (714) 494-9515