Work Life Insurance vs Private Insurance: What Families Need to Know

Many people assume their work life insurance is enough. But here’s the truth: employer coverage often leaves families exposed. It may sound reassuring, but when tragedy strikes, work life insurance rarely provides the lasting protection your loved ones need.

Executive Summary

  • Employer coverage is annual renewable term (ART), accidental death only, capped at 1-3x salary, and lost if you leave your job.
  • Private insurance offers level premiums, living benefits, convertibility, estate planning advantages, and portability.
  • Families relying on work life insurance may need to tap into their 401(k)s, negatively effecting their retirement savings.
  • Healthy individuals miss out on Preferred or Elite ratings through group life, paying more than necessary. 
  • Private insurance isn’t always more expensive and it can be cheaper long‑term vs rising group premiums. 
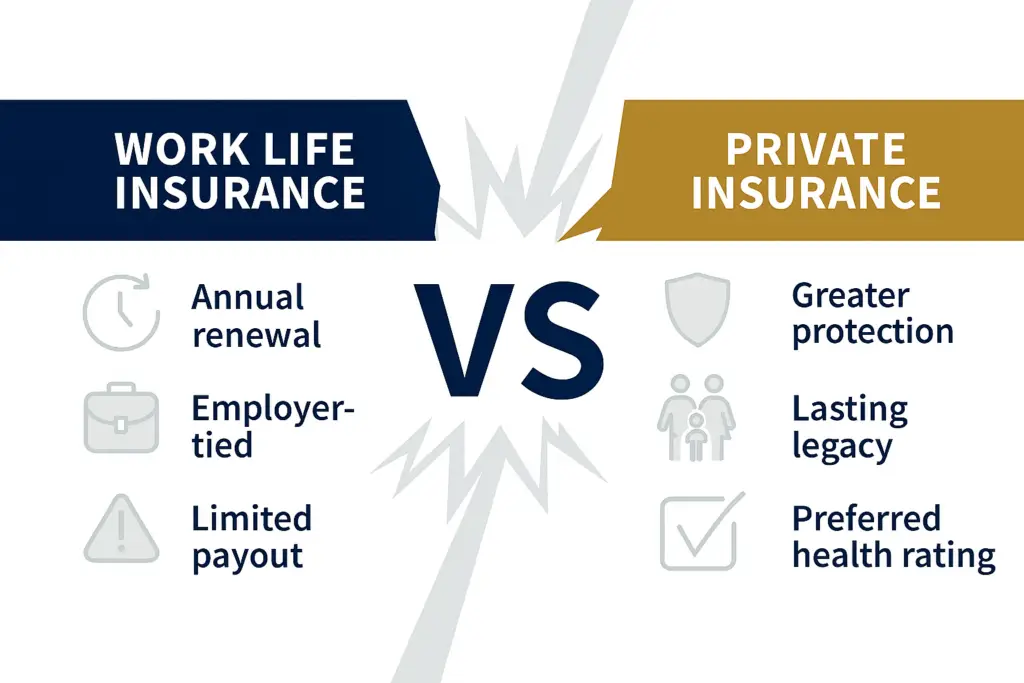
Side-by-side infographic comparing work life insurance and private insurance, highlighting key differences such as annual renewal, employer-tied limitations, and limited payout versus greater protection, lasting legacy, and preferred health rating. Designed for M&M Wealth Associates to educate consumers on the risks of relying solely on work life insurance.

How Work Life Insurance Works

Employer life insurance is usually annual renewable term coverage. That means the coverage resets each year and premiums rise as you age. Many plans only cover accidental death, leaving families unprotected against illness or natural causes.

Coverage is often capped at one to two times your salary, which rarely replaces income or secures long term goals. Even if you opt in for more coverage through your employer, restrictions can still prevent payouts in certain circumstances.

Most people don’t know this but when you leave your job, the coverage premium inflates significantly forcing many to terminate their coverage, often right when you need it most.

Why Private Insurance Is Different

Private life insurance, whether term or permanent, provides stability and flexibility that employer coverage cannot. Premiums can be locked in for 20 to 30 years, giving families predictable costs. Healthy individuals can qualify for Preferred or Elite ratings, lowering costs compared to group life. Policies often include living benefits that can help during illness or disability, and they can be converted to permanent coverage if your needs change.

Private insurance also provides estate planning advantages, with tax‑free death benefits that protect your legacy. Most importantly, it is portable. Your policy stays with you no matter where you work, ensuring that your family’s protection isn’t tied to your employment status. This independence makes private insurance a cornerstone of long‑term financial planning. 

Real World Risk: A Tale of Two Families

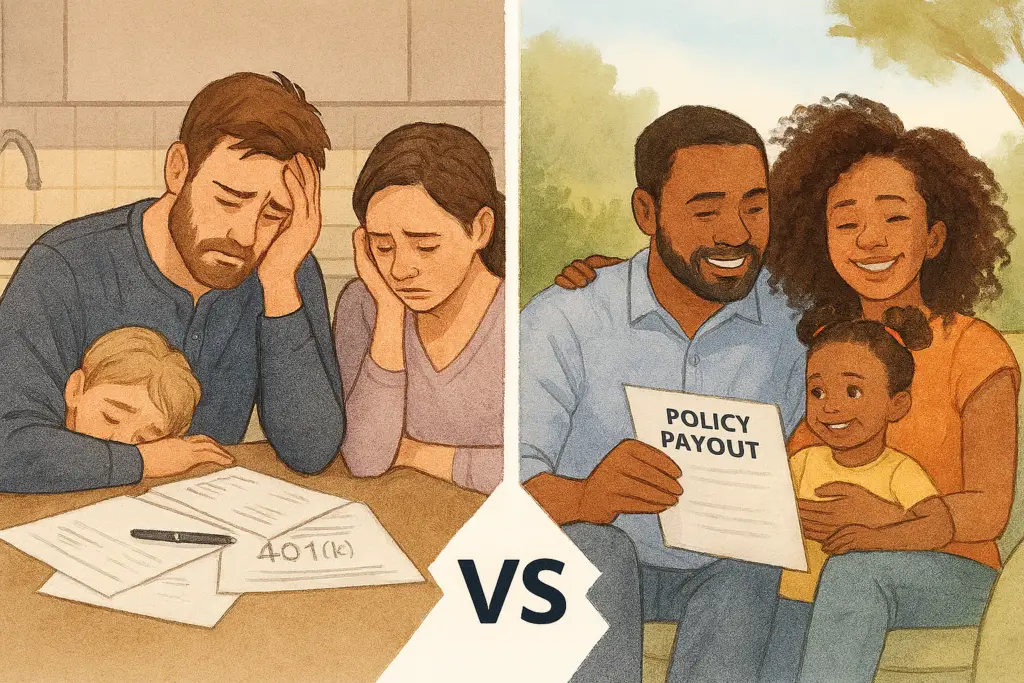
Consider two professionals, both earning $120,000. One relies on work life insurance, a $240,000 accidental death policy. When cancer strikes, the policy doesn’t pay. The family is forced to tap into their 401(k), draining retirement savings that were meant to compound for decades. Not only do they face mortgage payments, college tuition, and daily expenses with no safety net, but their retirement future is now jeopardized.

The other professional has a private $1 million term policy with living benefits. When tragedy hits, the payout covers expenses, preserves retirement accounts, and keeps the family financially stable. This contrast shows how employer coverage can leave families exposed, while private insurance provides lasting protection and peace of mind.
Busting the Cost Myth

Many believe private life insurance is more expensive than group coverage. In reality, group premiums rise as you age, making them more costly over time. Healthy individuals also miss out on Preferred or Elite ratings in group life, paying more than necessary.

Private term insurance can often cost the same or less than group coverage, while locking in rates for decades. The myth that private insurance is always more expensive simply isn’t true. For many families, private coverage is not only affordable but also the smarter long‑term choice.

Closing Thoughts

Work life insurance isn’t a fair comparison to private insurance. Employer policies may help in the short term, but they rarely provide the lasting protection families need. Relying solely on work coverage can leave families vulnerable, drain retirement accounts, and create financial stress during already difficult times.

At M&M Wealth Associates, we help clients understand their options and build coverage that fits their life, not just their job. Schedule a complimentary retirement strategy session today to explore how private insurance can support your long‑term goals and give your family the peace of mind they deserve.

Privacy Policy

M&M Wealth Associates values your privacy and is committed to helping make your experience with our website safe, secure, and informative. This Privacy Policy explains how we collect, use, and share information you provide when accessing or using our website.


Your Acknowledgement

This website is intended for use by individuals who are at least 18 years of age and who are accessing the website from within the United States.

By using this website or submitting information through it, you acknowledge that:

  • You are at least 18 years old.
  • You are accessing the website from within the United States.
  • You consent to the collection, use, and sharing of information as described in this Privacy Policy.

This Privacy Policy is incorporated into and subject to the website’s Terms of Use.


Information We Collect

We may collect both personally identifiable information (“PII”) and non-personally identifiable information (“Non-PII”).

Personally Identifiable Information (PII)

Examples include:

  • Name
  • Address
  • Email address
  • Phone number
  • ZIP code
  • Other information voluntarily submitted through forms or inquiries

Non-Personally Identifiable Information (Non-PII)

Examples include:

  • IP address
  • Browser type
  • Device information
  • Domain names
  • Access dates and times
  • Website usage data

For purposes of this Privacy Policy, both categories may be referred to collectively as “Information.”


How Information Is Collected

We may collect information when you:

  • Complete a contact form
  • Request information
  • Schedule a consultation
  • Access resources available through the website

We may also automatically collect certain information through cookies, browser information, analytics tools, and similar technologies.

Information automatically collected may include:

  • IP address
  • Browser type
  • Device identifiers
  • System type
  • Pages visited
  • Referring website addresses
  • Usage and navigation data

Cookies may be used to improve website functionality, personalize user experiences, and support website analytics.


How We Use Information

Information collected through the website may be used to:

  • Respond to requests and inquiries
  • Provide information and educational resources
  • Discuss insurance or financial products and services
  • Personalize communications
  • Improve website functionality and user experience
  • Maintain website security
  • Prevent fraud or misuse
  • Develop new services and website features
  • Fulfill legal and regulatory obligations

Information Sharing

We may share information with service providers and business partners who assist us in operating our business and servicing client needs.

We may also disclose information when:

  • Required by law
  • Responding to court orders, subpoenas, or regulatory inquiries
  • Protecting our rights, property, or safety
  • Investigating fraud, abuse, or unlawful activity
  • Enforcing our website terms and agreements

Communications and Your Right to Opt Out

By submitting information through this website, you consent to being contacted through the information you provide, including by:

  • Telephone
  • Email
  • Mail
  • Text message, where permitted by law

You may opt out of future promotional communications at any time.

To request removal from promotional communications, please contact:

M&M Wealth Associates
2900 S Harbor Blvd, Suite 225
Santa Ana, CA 92704

Phone: (714) 494-9515

Please allow up to 10 business days for processing. Administrative or legally required communications may still be sent when permitted by law.


Information Security

We maintain reasonable administrative, technical, and physical safeguards designed to protect information from unauthorized access, use, disclosure, alteration, or destruction.

However, no method of transmission or storage is completely secure, and we cannot guarantee absolute security.

If a security incident occurs, we may notify affected individuals electronically when permitted by law.

If you believe website security has been compromised, please contact us at:

(714) 494-9515


Changes to This Privacy Policy

M&M Wealth Associates reserves the right to update or modify this Privacy Policy at any time.

Changes become effective immediately upon posting to the website. Continued use of the website constitutes acceptance of any updated Privacy Policy.


Contact Us

If you have questions regarding this Privacy Policy, please contact:

M&M Wealth Associates
2900 S Harbor Blvd, Suite 225
Santa Ana, CA 92704

Phone: (714) 494-9515