Update on the Kyle Busch Lawsuit and Why It Matters for Policyholders
The Kyle Busch lawsuit against Pacific Life centers on several Indexed Universal Life policies the Busches say were misrepresented as secure, low‑risk retirement vehicles. Their complaint alleges significant losses after paying millions in premiums, while Pacific Life’s recent response argues the couple misunderstood how the policies worked and failed to manage them over time.
If you have not read the first part of this series, you can review our earlier article that explains the original allegations and how the case began. This follow‑up builds on that foundation and highlights the key developments in Pacific Life’s response, along with practical insights for anyone who owns or is considering an IUL policy.
Executive Summary
- Pacific Life has formally responded to the Kyle Busch lawsuit, arguing the couple misunderstood and mismanaged their Indexed Universal Life (IUL) policies.
- The case highlights how even high‑net‑worth families can make costly mistakes when policies are not reviewed, vetted, or fully understood.
- IULs are not guaranteed retirement plans. They are life insurance contracts with cash accumulation potential that require proper design, funding, and ongoing monitoring.
- These policies contain multiple moving parts, and misunderstanding them can lead to disappointment or unwanted outcomes.
- Misrepresentation in the insurance marketplace is a real risk, especially since insurance sales are not held to fiduciary standards.
- Consumers can protect themselves through annual reviews, second opinions, and a clear understanding of how their policy is structured and performing.
Pacific Life’s Response and Where the Case Stands Now
Pacific Life has filed a formal response seeking dismissal of the lawsuit, stating that the Busches’ claims stem from misunderstanding the policies rather than any wrongdoing by the company. Their position is that the policies were not misrepresented and that the couple failed to manage or review them over several years.
The legal process is still ongoing, and no final determination has been made.
Even High‑Net‑Worth Families Must Do Their Homework
The Kyle Busch lawsuit reveals a reality many consumers overlook. Being wealthy and/or famous does not replace due diligence. Even with access to advisors, attorneys, and financial professionals, it is still possible to:
- Misunderstand how a policy works
- Rely too heavily on a single agent’s explanation
- Skip getting a second opinion
- Miss red flags in policy design or funding
This is not unique to celebrities. Everyday consumers face the same risks when they rely solely on sales presentations without deeper evaluation. Read this article about IUL Sales and Bad Practices.
IULs Are Powerful Tools, but They Are Not Guaranteed Retirement Plans
Indexed Universal Life policies are valuable when used correctly, but misunderstanding their purpose is the most common issue in the marketplace.
What an IUL actually is
- A life insurance contract
- A policy with cash accumulation potential
- A tax‑advantaged tool that can supplement retirement income
- A product tied to index crediting strategies, not direct market participation
What an IUL is not
- A guaranteed retirement plan
- A risk‑free investment
- A substitute for a diversified portfolio
- A set‑and‑forget financial product
Misalignment between expectations and reality is often where frustration begins.
Why These Policies Require Ongoing Review
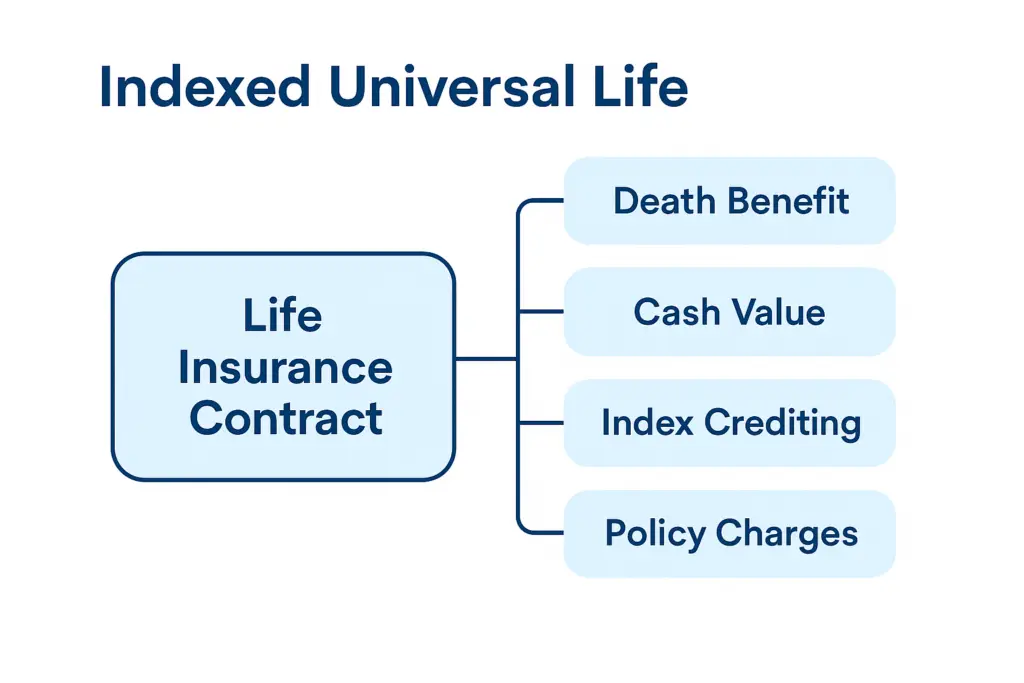
IULs are not simple, rather they are quite complex. They require monitoring because they contain multiple levers that influence performance.
Key elements that must be reviewed regularly
Death Benefit Structure
Premium funding strategy
Index crediting method
Policy charges and cost of insurance
Riders and their impact
Overall policy health and sustainability
Going several years without reviewing a policy is risky. Annual reviews help ensure the policy is performing as expected and allow adjustments before issues compound.
The Real Risk: Misrepresentation and Under‑Regulated Sales Practices
The Kyle Busch lawsuit also highlights a broader industry issue. Insurance sales are not held to fiduciary standards, meaning agents are not required to act in the client’s best interest in the same way investment advisors are.
Common marketplace risks:
- Policies sold as “stand-alone retirement plans” rather than a diversification tool
- Overemphasis on upside potential with unproven volatility controlled indexes
- Under‑disclosure of costs, risks, and moving parts
- Illustrations shown at unrealistic crediting rates
- Consumers not being told what to monitor over time
If something sounds too good to be true, it usually is. This is where consumers must be cautious.
Closing Thoughts and What You Should Do Next
The Kyle Busch lawsuit is a reminder of how important it is to stay engaged with any permanent life insurance policy, especially one as flexible and complex as an IUL. These policies can be powerful tools, but they work best when they are properly designed, adequately funded, and reviewed on a regular basis. Taking time each year to look at how your policy is performing, how it is structured, and whether it still aligns with your goals can prevent surprises and keep your long‑term plan on track.
If you own an IUL or are considering one, it is helpful to ask clear questions about how the indexing strategy works, what drives the policy’s costs, and how your premium strategy supports the long‑term sustainability of the contract. Requesting updated illustrations and seeking a second opinion can also provide clarity and confidence, especially when the policy is intended to support retirement income or legacy planning.
As a courtesy, you can use our scheduling link to request a policy review and ensure your coverage is doing what it should be doing. A little proactive attention today can make a meaningful difference in how your policy performs over time.