Why High Earners Often Feel Frustrated at Tax Time
Every single year, high-income earners across the country have the same reaction when tax season arrives: “I’M PAYING HOW MUCH?!” After a year of hard work, blood, sweat, and tears, they generated meaningful income only to watch a significant portion of it disappear in taxes.
Have you ever wondered if you’re paying more than you should? In many cases, the issue is not how much you make. It’s that tax planning never became part of the conversation. The good news is that there are legitimate tax strategies for high earners that can help improve tax efficiency, but most people don’t learn about them until years after they could have benefited from them.
Executive Summary
- Most high earners do not have a tax filing problem, they have a tax planning problem.
- Tax filing reports what already happened. Tax planning helps influence future outcomes.
- The tax code rewards proactive decisions made throughout the year, not last-minute reactions during tax season.
- Retirement accounts, investment strategies, charitable giving, business planning, and real estate can all impact tax efficiency.
- The biggest opportunities often come from coordinating multiple areas of your financial life rather than focusing on a single strategy.
- The goal is not to avoid taxes. The goal is to avoid paying more than necessary.
- The earlier planning begins, the more options you typically have available.
Why High Earners Often Overpay
Most professionals become experts in their field, and typically not experts in the tax code. Physicians focus on patients, business owners focus on growth, and executives focus on leadership. Taxes often become something you deal with once a year rather than something they actively plan for.
The challenge is that the tax code rewards preparation. By the time most people sit down with their CPA, many opportunities to improve their tax situation have already passed.
Tax Filing vs. Tax Planning
One of the biggest misconceptions is believing that filing taxes and tax planning are the same thing, THEY ARE NOT. Tax filing documents the decisions you’ve already made, while tax planning helps guide the decisions you haven’t made yet.
Effective tax planning happens throughout the year. It considers how you earn income, where you save money, how you invest, when you recognize gains, and how all those decisions impact your overall financial picture.
Common Planning Opportunities High Earners Miss
Many high earners contribute to a retirement account and assume they’ve covered their tax planning responsibilities. While that’s a good start, it is often only one piece of a much larger puzzle. Additional opportunities may exist through retirement plans, Health Savings Accounts, charitable giving strategies, business planning, and investment management.
In some cases, business owners may benefit from advanced retirement strategies such as defined benefit plans, which can create substantial tax planning opportunities when appropriately designed. Learn more about defined benefit plans for business owners.
Investment decisions can also have a significant impact on taxes. Many people focus exclusively on returns, but what ultimately matters is how much of those returns you get to keep after taxes are accounted for.
Looking Beyond This Year's Tax Return
Some of the most effective tax strategies require thinking several years ahead. Rather than asking how to reduce taxes this year, successful planners often ask: “How do I minimize my total tax burden over the next 5, 10, or even 20 years?”
Taking a longer-term view can create opportunities that may not be obvious when looking at a single tax return. Sometimes the best strategy is not the one that produces the lowest tax bill today, but the one that creates the best overall outcome over time.
Why Coordination Matters
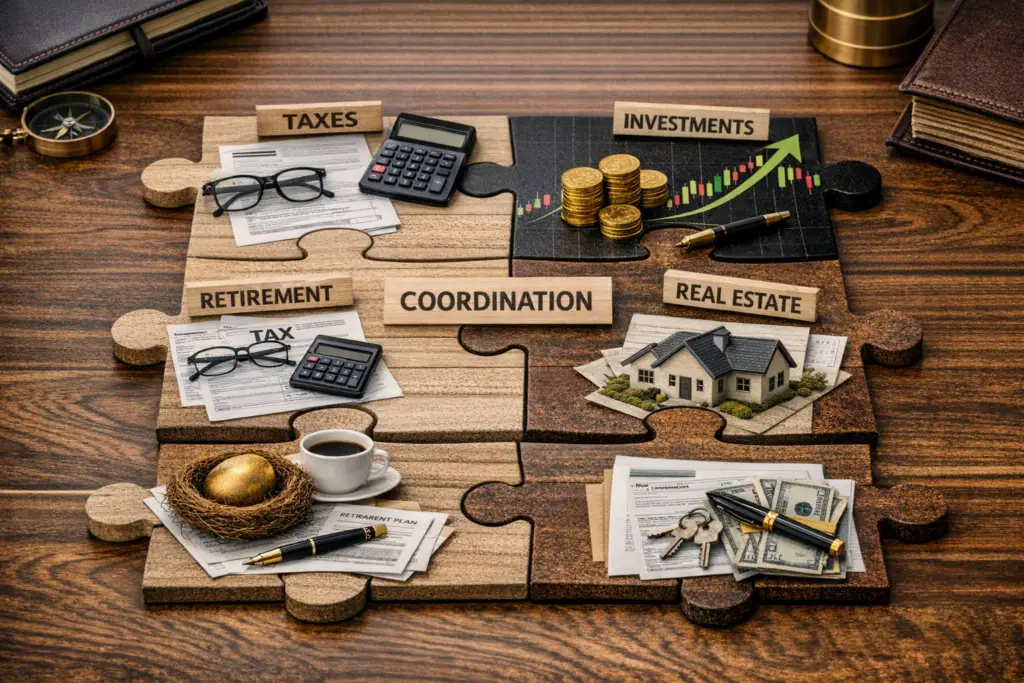
In my experience, most people do not have a tax problem, they have a COORDINATION PROBLEM. Their CPA focuses on taxes, their investment advisor focuses on investments, and their attorney focuses on legal planning. Each professional may be doing an excellent job, but the bigger picture is often overlooked.
The strongest financial strategies are rarely built around one idea. They come from multiple areas of planning working together toward a common objective.
The Bottom Line
If you feel like you’re paying more in taxes than you should, there’s a good chance you’re right. The good news is that reducing taxes is not about finding loopholes or chasing complicated strategies. It’s about becoming more intentional and proactive with the decisions you’re already making.
Tax planning is not a once-a-year event. It is an ongoing process. The earlier you begin planning, the more options you typically have available and the more control you may have over your long-term financial future.
Disclaimer: This article is for educational purposes only and should not be construed as tax, legal, or accounting advice. Please consult qualified professionals regarding your specific situation.